
Two days after the US Senate failed to advance the CLARITY Act, federal regulators opened two narrower routes for crypto-linked market access under existing law.
The Securities and Exchange Commission created a five-year path for permissioned venues to trade tokenized US stocks through automated market makers. The Commodity Futures Trading Commission broadened staff no-action relief so qualifying software providers can connect users to regulated derivatives markets without registering as introducing brokers for the covered activity.
The actions can support real products, but they do not recreate market-structure legislation. The SEC route is capped and conditional. The CFTC route still relies on registered derivatives firms for onboarding, trading and custody, and it rests on a staff position that can change.
The SEC turns existing authority into a five-year test
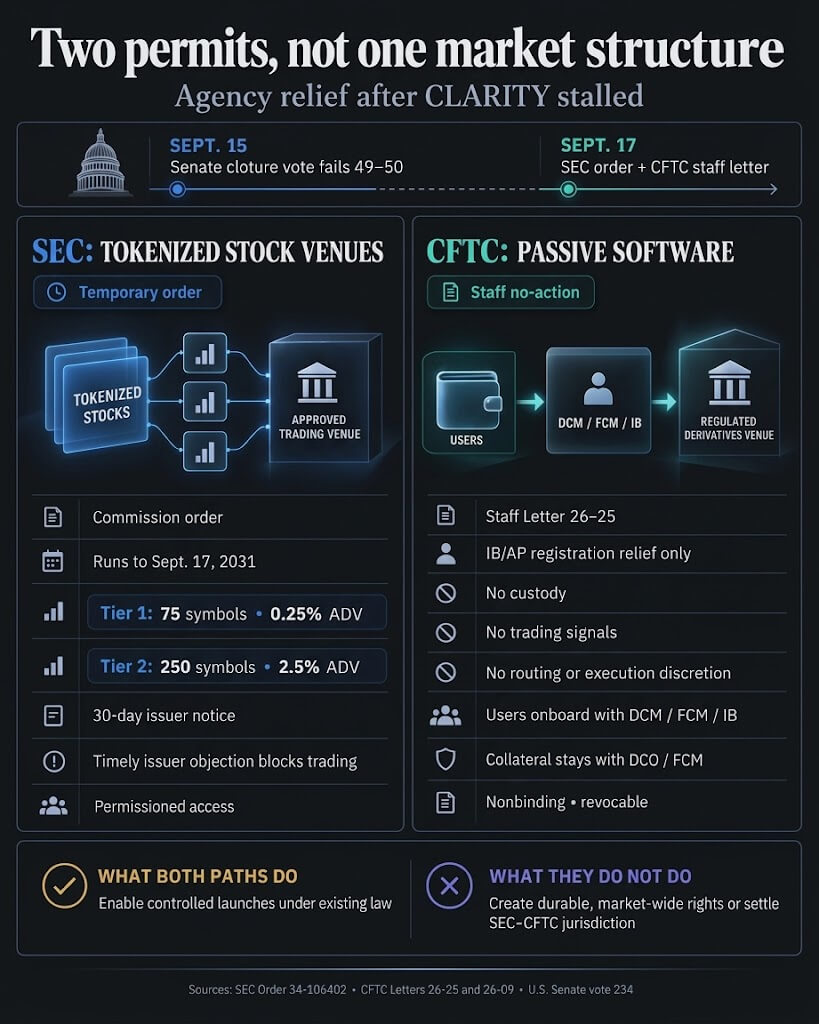
The timing was direct. On Sept. 15, senators voted 49-50 against cloture on the motion to proceed to H.R. 3633, according to the official roll call. That was a procedural failure to advance the CLARITY Act, not a final vote on the bill’s merits.
On Sept. 17, SEC Chairman Paul Atkins connected the congressional setback to the Commission’s next move. In a statement accompanying the Innovation Exemption, Atkins said the agency was acting within its existing statutory authority. He also characterized the exemption as a bridge that should be followed by durable rulemaking.
The SEC order creates a new category called a Tokenized Securities Venue, or TSV. A qualifying venue can bring buyers and sellers together through permissioned automated market maker liquidity pools without being treated as an exchange under the Exchange Act. Certain firms that supply tokenized stock from proprietary accounts can also receive conditional relief from the dealer definition for that activity.
The exemptions run through Sept. 17, 2031, unless the SEC modifies them. Their limits make the experiment deliberately small relative to the US equity market.
Across a TSV and its affiliates, Tier 1 stocks are limited to 75 symbols and no more than 0.25% of the prior month’s average daily share volume in each relevant stock. Tier 2 stocks are limited to 250 symbols and 2.5% of average daily share volume.
Eligible tokenized stocks must preserve the economic and governance rights attached to equivalent traditional shares, including dividend and voting rights. Synthetic-exposure tokens, rights, warrants, primary issuances and initial offerings do not qualify.
Issuers also receive a direct control point. Before a TSV can trade stock tokenized by an unaffiliated third party, the venue must notify the issuer and wait at least 30 calendar days after receipt. An objection delivered within that window blocks the tokenized stock from trading on that TSV.
The blockchain may be public and permissionless, but the market is permissioned. TSVs must set access standards, verify participants or wallet addresses, and disclose when access can be denied or limited. Smart contracts must be public and auditable, while the venue remains responsible for delegated verification.
The order replaces full exchange oversight with tailored conditions rather than removing market safeguards. TSVs must publish transaction data, keep records, stop trading when the underlying stock is halted on its primary exchange, disclose operational risks and report significant systems events.
Other laws still apply. The order preserves Securities Act requirements, federal antifraud and antimanipulation rules and sanctions compliance. SEC, self-regulatory organization and anti-money laundering duties can still apply to participants based on their activities. The exemption covers the defined TSV model, not securities activity outside it.
The CFTC opens an interface while registered firms keep control
The Commodity Futures Trading Commission‘s Market Participants Division moved on the same day with Letter 26-25. The letter generalizes relief that the division granted to Phantom in Letter 26-09 in March. The earlier position applied only to Phantom; the new one is available to passive software providers on substantially the same terms and is not limited to crypto wallets.
A qualifying provider can display market and position data, market particular derivatives contracts and registered firms, solicit users, receive revenue sharing or transaction-based fees, and transmit user-directed orders. Those activities could otherwise trigger introducing-broker or associated-person registration.
The relief is narrow. The software provider cannot hold customer assets, generate express buy or sell signals, or exercise discretion over order routing or execution. Letter 26-25 addresses only whether the division will recommend enforcement for failure to register as an introducing broker or associated person for the covered activities. It does not provide a general exemption from other registration categories or laws.
Users must be onboarded directly with a designated contract market, futures commission merchant or introducing broker. They must be able to reach that registered firm independently of the software provider. Funds securing derivatives positions remain with a derivatives clearing organization and/or a clearing-member futures commission merchant.
The provider also assumes conditions covering conflict and risk disclosures, marketing controls modeled on National Futures Association rules, recordkeeping, regulatory notices and joint liability with each participating registrant for violations connected to the covered activity.
This creates a clearer role for wallets and other interfaces without moving the regulated market’s core functions into the software layer. A provider can make derivatives easier to discover and access, but the designated market handles trading, registered firms onboard users, and a DCO or FCM holds collateral.
The legal foundation is also less durable than the SEC’s time-limited Commission order. Letter 26-25 represents the views of one CFTC division, is not binding on the Commission and may be modified, suspended or terminated. Unless changed earlier, it runs only until relevant Commission rulemaking or guidance takes effect.
Useful permits still fall short of market structure
The SEC and CFTC actions solve different registration problems. Their shared feature is that both create conditional operating space without establishing general market-wide rights.
For tokenized stocks, access depends on a TSV’s permissioning standards, symbol and volume caps, issuer objections and continuing compliance with the order. For regulated derivatives, the interface provider must remain passive while users, collateral and execution stay inside registered market infrastructure.
That distinction makes the new routes useful for controlled launches. A firm can build to specified conditions instead of waiting for Congress. Users may gain easier paths to tokenized stocks or regulated derivatives. Regulators can observe activity before writing permanent rules.
The same design creates uncertainty. Neither action settles the broader allocation of authority between the SEC and CFTC. Neither grants an unconditional right for a venue, wallet or user to enter these markets. Other applicable federal and state obligations remain outside the narrow relief, and future agency interpretations could change the economics of relying on it.
No company is named in the SEC order or CFTC Letter 26-25 as committed to launch under the Sept. 17 pathways. The CFTC letter says only that unnamed similarly situated providers and their counsel made inquiries after the Phantom relief.
The first practical test will be public commitments. For the SEC route, that means notices from operators willing to accept the caps, disclosure duties and issuer-objection process, followed by evidence that liquidity can develop within those limits. For the CFTC route, it means software providers signing agreements with registered derivatives firms, filing the required undertakings and offering an interface that remains passive in practice.
Market behavior will then reveal whether conditional access can scale. Issuer objections, participant onboarding, liquidity, transaction volumes and any regulatory modifications will show whether the pathways become durable market channels or remain experiments.
The agencies have demonstrated that US crypto access can grow without a new act of Congress. They have not shown that temporary exemptions and revocable staff relief can provide the certainty, uniformity or jurisdictional settlement that legislation could deliver.
The post SEC and CFTC bypass Congress to open crypto access after CLARITY fails – with a catch appeared first on CryptoSlate.