
Europe’s central banks want the European Union to rethink a rule designed to make stablecoins safer, but that can also link a token run directly to the banking system.
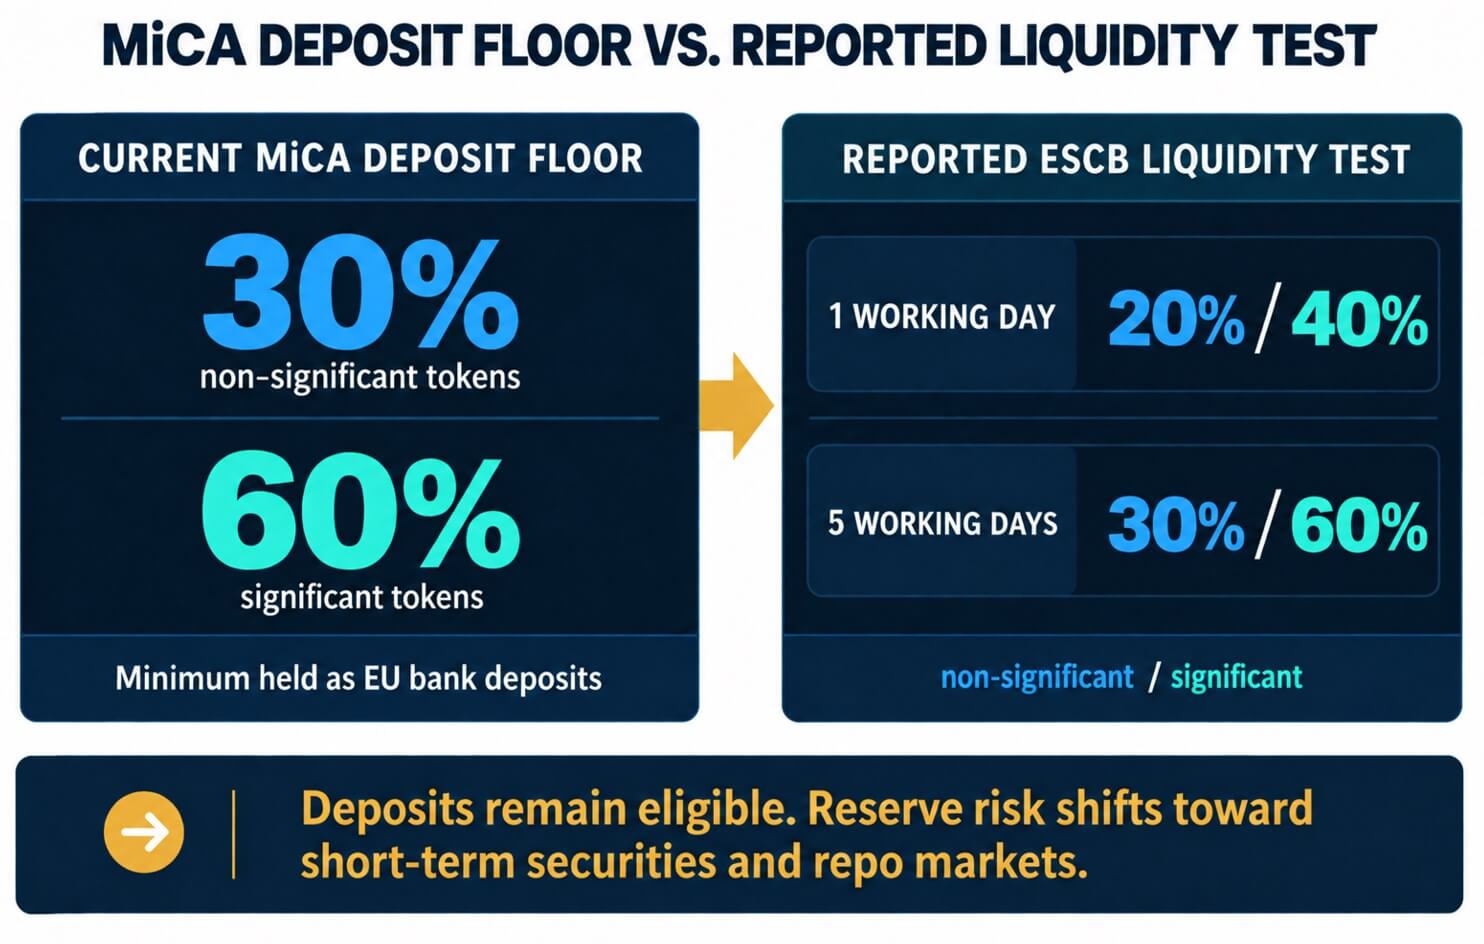
For reserve amounts tied to official currencies, MiCA currently requires issuers of non-significant tokens to keep at least 30% as deposits with EU credit institutions. The floor rises to 60% for significant tokens, according to the European Banking Authority’s technical standards.
Reuters and Cinco Días reported Sept. 22 that the European System of Central Banks wants that fixed minimum removed. Deposits would remain eligible, while reserve safety would turn on how much could become cash within one or five working days.
The position is input to the European Commission’s review of the Markets in Crypto-Assets Regulation. The consultation runs through Sept. 30, and the Commission says the responses may inform a later legislative proposal.
That leaves a policy question open: can Europe loosen the link between stablecoins and bank funding while preserving the liquidity needed for redemptions?
How MiCA’s deposit floor creates a two-way channel
Bank deposits give an issuer cash it can use when token holders redeem. Yet a deposit is also a claim on a bank, and a mandatory allocation makes the token’s reserve quality partly dependent on the condition of the institutions holding that money.
During the March 2023 banking turmoil, Circle held part of USDC’s reserves at Silicon Valley Bank, and uncertainty over access to those funds pressured the token’s peg. USDC’s market capitalization fell 26% over a month, according to an ECB analysis.
An issuer facing heavy withdrawals may pull large bank deposits at once, so stablecoin reserves that had looked like funding to a receiving bank can then behave like flighty wholesale money.
An ECB speech described how redemptions could force a stablecoin issuer to withdraw reserves and pressure a bank’s liquidity. An ECB working paper added that issuers may concentrate their deposits among a small number of banks.
Euro-denominated stablecoins had a market capitalization of about €450 million in January 2026, compared with roughly $300 billion for dollar-denominated tokens. Crypto-platform and stablecoin deposits also remain small relative to the assets of exposed euro-area banks.
The policy concern centers on the concentration and behavior of reserve deposits if adoption grows.
A fixed quota can create two reciprocal exposures. Bank distress can impair the reserves behind a token, while a token run can drain a bank’s funding. The rule improves immediate access to money in ordinary conditions, but it also determines where stress first lands.
The reported ESCB alternative focuses on the redemption timetable. For official-currency tokens, it would use existing EBA liquidity buckets: at least 20% of reserves available within one working day and 30% within five days for non-significant tokens.
The thresholds rise to 40% and 60% for significant tokens. Those tests preserve a near-cash buffer while allowing issuers to meet it with a broader regulated mix of assets.
What a maturity test changes
The proposal would replace a rule about where a set share of reserves must sit with a test of how quickly the whole reserve can produce cash.
| Feature | Current MiCA framework | Reported ESCB approach | Main effect |
|---|---|---|---|
| Bank deposits | At least 30% for non-significant tokens and 60% for significant tokens | No fixed minimum deposit share | Deposits remain eligible while issuers gain allocation flexibility |
| One-day liquidity | Part of the wider reserve framework | At least 20% for non-significant tokens and 40% for significant tokens | Tests immediate redemption capacity |
| Five-day liquidity | Part of the wider reserve framework | At least 30% for non-significant tokens and 60% for significant tokens | Adds a broader near-cash buffer |
| Reserve exposure | A mandated share sits with commercial banks | More room for short-term securities and reverse repos | Bank linkage falls as market exposure rises |
Under the EBA framework, withdrawable cash and reverse repurchase agreements that can be terminated within the relevant window can count toward the thresholds. Specified highly liquid financial instruments can also qualify, while short maturity alone does not make an asset eligible.
The EBA uses Liquidity Coverage Ratio categories to identify eligible instruments. Core Level 1 sovereign and public-sector assets sit in a 0% reference-haircut category, while extremely high-quality covered bonds carry a reference haircut of at least 7%.
For reserve valuation, the rules disapply those haircuts and instead require overcollateralization to cover market-value risks.
Draft safeguards cap an issuer’s deposit at one systemically important bank at 25% of reserves and 1.5% of that bank’s total assets. Qualifying securities and money-market instruments in the 0% reference-haircut category are capped at 35% of reserves when they come from one issuer.
The change could improve issuer economics because short-term sovereign paper or repo positions may earn more than bank deposits. The result would likely shift some reserves, income, and risk toward government-debt and funding markets.
Issuers would still have to satisfy liquidity, asset-quality, concentration and overcollateralization controls.
An issuer holding short-term sovereign debt or an overnight reverse repo has less direct exposure to the failure of a particular deposit-taking bank. A redemption wave would be less likely to begin with the withdrawal of one large wholesale deposit.
Heavy redemptions can force securities sales or repo unwinds. Concentrated holdings can carry stablecoin stress into sovereign or funding markets, while falling bond prices can weaken reserve values in the opposite direction.
The ECB’s analysis of stablecoin demand for sovereign debt says the effect depends on the issuer type, its asset mix, and the sector that supplied the money used to buy the token.
Reserve design therefore allocates rather than abolishes risk. A maturity-based rule may reduce the direct bank channel, but its safety depends on the credit quality, market depth and concentration of the assets used to meet redemptions.
Tether wins one policy argument while licensing stays separate
Tether CEO Paolo Ardoino said the reported ESCB position echoed Tether’s warning about MiCA’s mandatory bank-deposit share. On that point, the company said that concentrating reserves in commercial banks can transmit distress between an issuer and a lender.
Tether’s European position includes concerns about restrictions on non-euro stablecoins and other MiCA features. The company also wound down euro-backed EURT while calling for a more risk-averse framework, and USDT remains outside the group of tokens issued under a MiCA authorization.
Removing the deposit floor would leave the broader regime in place. Issuers would still face requirements covering authorization, governance, capital, audits, reserve segregation, redemption, and prudential supervision.
The proposal would neither confer an EU authorization on USDT nor settle Tether’s broader objections to the framework.
The more consequential shift concerns control over reserve allocation. Commercial banks would lose a guaranteed share of official-currency reserves, while issuers would gain discretion within a regulated menu of deposits, short-term securities and repo arrangements.
Sovereign-debt and funding markets could receive a larger share of the assets and yield as a result.
Europe’s decision is ultimately about the architecture of redemption safety. A deposit quota emphasizes the location of reserves and anchors much of it inside banks, while a maturity test emphasizes how quickly a diversified reserve can turn into cash.
The reported ESCB position favors the second model while retaining limits on eligibility, concentration and collateral.
That framework can weaken one link in the contagion chain. Its success would depend on whether issuers can meet redemptions under stress without turning a stablecoin run into disorderly sales elsewhere in the financial system.
The post EU central banks attack MiCA rules and stablecoin runs are blamed appeared first on CryptoSlate.