
Bitcoin options expiring Friday carry substantial put exposure below the market price, while short-term volatility pricing has fallen ahead of Wednesday’s US inflation report.
Data from Coinbase-owned Deribit, a crypto options exchange, showed that in an Oct. 12 snapshot the Oct. 16 settlement carried approximately 15,502 BTC in outstanding options, comprising 9,128 BTC in puts and 6,373 BTC in calls. The put-to-call ratio stands at 1.43, with about $451 million in underlying notional exposure concentrated in puts at $76,000, $78,000 and $80,000.
The snapshot put Bitcoin near $83,450 after last week’s selloff, while derivatives platform Laevitas reports declining short-term volatility expectations ahead of the Consumer Price Index (CPI) release.
Bitcoin puts cluster between $76,000 and $80,000
Deribit’s options data shows the largest concentration of puts at the $80,000 strike, with outstanding contracts carrying about $188 million in underlying notional exposure.
Another $162 million is concentrated at $78,000, while the $76,000 strike accounts for approximately $101 million.
Combined, the three levels represent nearly 35% of the $1.29 billion options expiry, highlighting the scale of downside positioning after Bitcoin briefly fell toward $80,000 during last week’s market downturn.
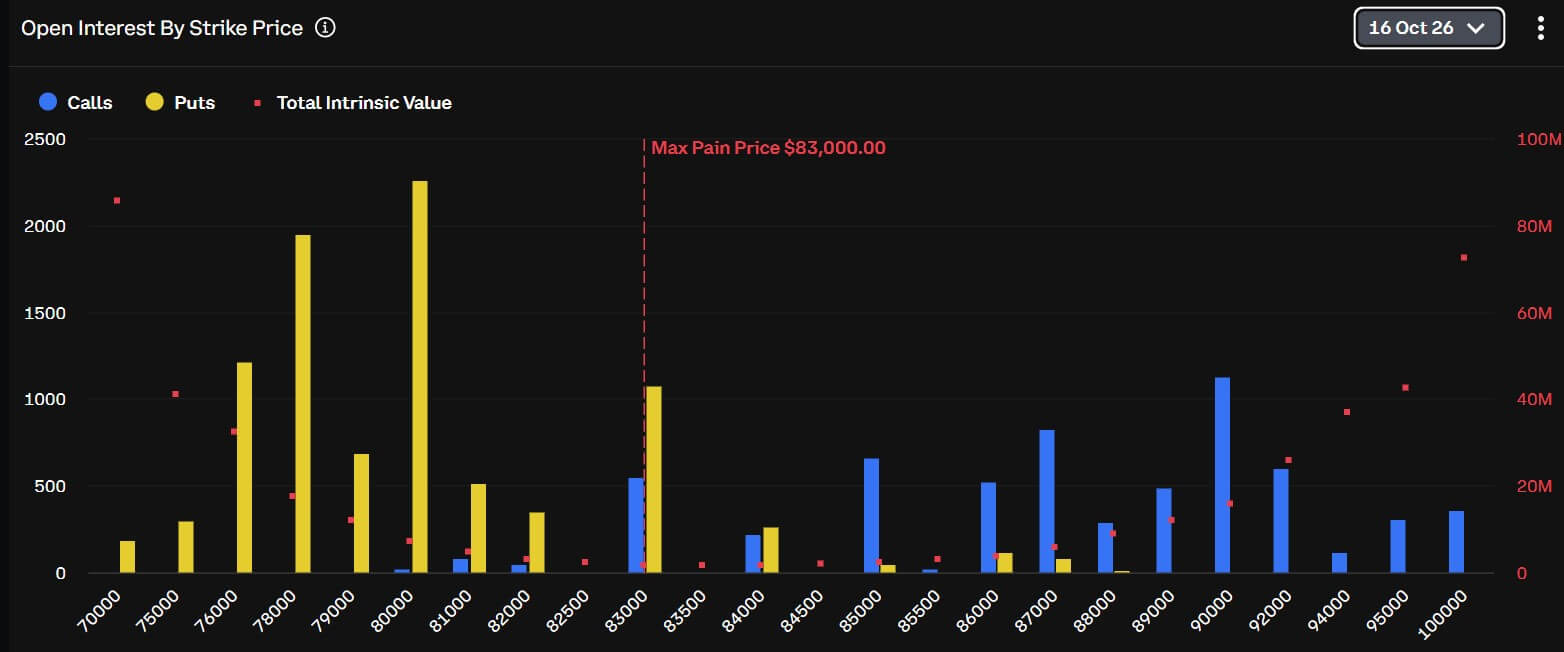
Additional put exposure worth about $89 million is concentrated at $83,000, near Bitcoin’s current trading price.
The concentration suggests traders remain concerned about renewed selling pressure, although put open interest also includes contracts sold by investors seeking to collect premiums rather than exclusively buyers seeking protection.
Deribit data shows approximately $94 million in call exposure at $90,000, followed by $70 million at $87,000 and $55 million at $85,000.
Together, the three levels account for $219 million in outstanding notional exposure, less than half the amount concentrated at the three major downside put strikes.
The distribution leaves Bitcoin’s largest downside positions relatively close to prices tested during the recent decline, while the $90,000 call strike requires an advance of nearly 8% from current levels.
Meanwhile, Deribit’s maximum pain calculation stands at $83,000, indicating the settlement level that would minimize the aggregate intrinsic value of outstanding options based on current positioning.
Later-dated Bitcoin options also carry substantial upside exposure: Deribit’s Oct. 30 expiry has approximately $4.54 billion in call notional across the $90,000, $95,000 and $100,000 strikes.
Bitcoin volatility expectations retreat before Wednesday’s CPI
Laevitas’s Oct. 12 brief described a volatility curve that prices Wednesday’s CPI as a non-event.
Bitcoin’s seven-day at-the-money implied volatility declined to 32.01% from approximately 34.5% a week earlier.
That compares with 34.66% for 30-day contracts, 37.29% for 90-day options and 38.24% for 180-day maturities.
For illustration, converting the annualized seven-day implied volatility to a weekly move at the $83,450 snapshot price gives a one-standard-deviation move of roughly 4.4%, or $3,700, under conventional volatility assumptions.
That would place the modeled weekly range between approximately $79,750 and $87,150, encompassing the $80,000 put strike but falling short of the substantial call concentration at $90,000.
Meanwhile, Laevitas reported that Bitcoin’s seven-day 25-delta options skew shifted from +1.98 to -2.40 over the past week, a 4.38-point reversal.
Laevitas characterized the move as an unwind from a call-bid extreme toward nominally put-bid pricing, with puts still cheaper relative to calls than their 52-week median.
Bitcoin perpetual-futures open interest fell 1.9% over the past week to approximately $29.33 billion, while annualized funding rates stood at 5.6%, according to Laevitas.
The positioning comes as investors assess whether US inflation could prompt the Federal Reserve to raise interest rates again at its Oct. 27-28 policy meeting.
MarketWatch’s Oct. 12 preview cited expectations for September headline inflation to accelerate to approximately 3.7% annually from 3.4% in August, partly reflecting higher energy costs. Monthly core inflation, which excludes food and energy, is forecast to rise 0.2%.
Laevitas described an October increase as close to priced out, with December pricing around an 85% probability of a hike.
However, elevated oil prices and Treasury yields continue to complicate the outlook for risk assets, with stronger-than-expected inflation potentially reviving expectations of another rate increase.
In illustrative price scenarios, hotter inflation could pressure Bitcoin toward the heavily populated $78,000–$80,000 put strikes, while softer inflation could encourage a recovery toward the higher call concentrations.
The CPI report arrives Wednesday, Oct. 14, at 8:30 a.m. Eastern Time, followed by producer-price inflation and retail-sales data Thursday, Oct. 15, giving traders two days of economic releases to absorb before Friday’s $1.29 billion options expiry.
The post Bitcoin options price a quiet CPI week while shorts cluster at $76,000–$80,000 appeared first on CryptoSlate.